|
Photo: VASEP/FIS
Vietnam Seafood Exports Top $1 Billion in July but Face Slowdown Over US Tariffs
 (VIET NAM, 8/7/2026) Section 301 tariff hikes, competition from Ecuador, and new regulatory requirements in Europe project a complex scenario for the final stretch of 2026.
HANOI — Vietnam's seafood exports reached nearly US$1.02 billion in July 2026, representing a 4.8% growth compared to the same period in 2025. With this result, the cumulative value for the first seven months of the year rose to nearly US$6.78 billion, equivalent to an 11.5% year-on-year expansion. Although the monthly figure consolidates the sector's projection of exceeding US$12 billion by the end of the annual exercise, the data reflects a cooling in the pace of commercial expansion.
 FIS Seafood Media(2).jpg)
According to a report prepared by Le Hang, Deputy Secretary General of the Vietnam Association of Seafood Exporters and Producers (VASEP), the period of most accelerated growth appears to have concluded. Exports of pangasius (Pangasianodon hypophthalmus) recorded a 6.1% decline in July, while tuna shipments (Thunnus / Katsuwonus pelamis) remained virtually flat. Likewise, shipments to the European Union, South Korea, and the Middle East suffered double-digit contractions.
Compounding this slowdown is the regulatory impact in the United States, where starting July 24, Vietnamese seafood products became subject to an additional tariff of 12.5% under Section 301. Although contract deadlines and shipping times prevented this surcharge from being fully reflected in July's figures, VASEP anticipates that its effect will become noticeable starting in August and throughout the fourth quarter.
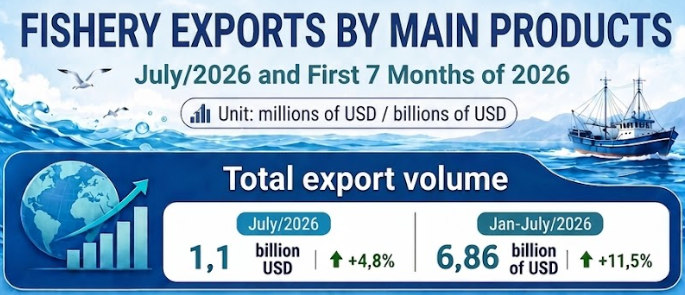
Source: VASEP
Competition in the Shrimp Sector and Tariff Pressure
Shrimp exports reached over US$428 million in July (+4.5%), accumulating nearly US$2.78 billion in the first seven months of the year (+12.6%), which accounts for approximately 41% of total turnover for Vietnam's fisheries sector. However, the 4.5% monthly growth was considerably below the period average, driven mainly by lobster shipments to China. In contrast, traditional species such as whiteleg shrimp (Litopenaeus vannamei) and tiger shrimp (Penaeus monodon) face fierce competition in the United States, the European Union, and Japan.

Source: VASEP
The main pressure comes from Ecuador, a country that has substantially increased its supply not only of head-on shrimp, but also of headless, peeled, and processed products with higher added value. Adding to this direct competition factor is the tax disadvantage in the US market: pursuant to the United States Trade Representative (USTR) decision of July 23, shipments from Vietnam are taxed at a 12.5% rate under Section 301, while direct competitors such as Ecuador, India, and Indonesia are subject to a 10% tariff.
.jpg) 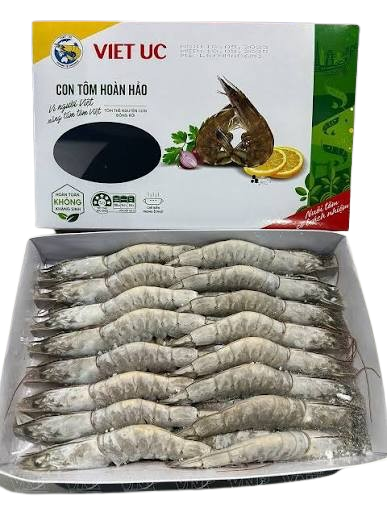
Photo: stockfile/ FIS
This 2.5 percentage point difference, combined with tariffs under the Most Favored Nation (MFN) clause and potential anti-dumping or countervailing duties, puts pressure on frozen shrimp margins, prompting US importers to request FOB price reductions, cost-sharing schemes, or shorter contract terms.
Opportunities and Regulatory Challenges for Pangasius
In the pangasius (Pangasianodon hypophthalmus) segment, July shipments decreased by 6.1% to nearly US$184 million, although the cumulative total for the seven months reached US$1.3 billion (+8.8%). The monthly decline reflects an adjustment in Chinese demand for larger fish sizes and a still-moderate recovery in the US

Source: VASEP
Despite this situation, the species has a strategic window of opportunity amid the shortage of whitefish in the European market. High prices for Atlantic cod (Gadus morhua), haddock (Melanogrammus aeglefinus), and Alaska pollock (Gadus chalcogrammus) — resulting from lower catch quotas and restrictions linked to Russian supply — have prompted European Union processors to consider pangasius and tilapia as alternatives for frozen product lines and mass catering services.
However, VASEP warns that access to the European market is conditioned upon compliance with strict traceability requirements. Effective January 10, 2026, EU importers are required to submit catch certificates through the digital CATCH system for seafood products under Chapter 3 and headings 1604 and 1605 of the tariff nomenclature. Although farmed pangasius is not directly governed by this wild-catch certificate, administrative complications associated with wild harvests are reshaping the sector's competitiveness on the European continent.
(1).jpg) (1).png)
Photo: stockfile/ FIS
Performance of Tuna and Other Marine Products
The tuna (Thunnus and Katsuwonus pelamis) industry recorded exports of US$69 million in July (-0.1%), closing the first seven months at nearly US$524 million (-1.4%). The sector faces a dual impact in the United States: the 12.5% Section 301 tariff and the Marine Mammal Protection Act (MMPA) regulations, effective January 1, 2026.

Source: VASEP
The National Oceanic and Atmospheric Administration (NOAA) confirmed the denial of equivalence recognition for certain Vietnamese fisheries. Consequently, products originating from these areas must be accompanied by a mandatory Certificate of Admissibility (COA). In Europe, the sector continues to be impacted by the yellow card for Illegal, Unreported and Unregulated (IUU) fishing and the EVFTA rules of origin.

Source: VASEP
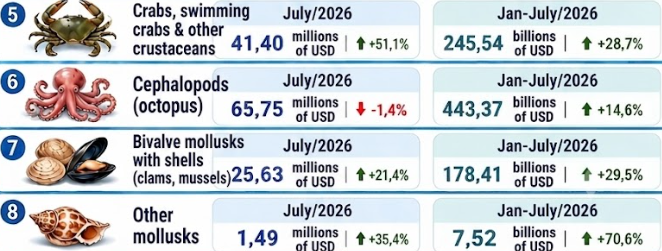
Conversely, the crab and crustacean group recorded a remarkable 51.1% increase in July (US$41 million), accumulating US$246 million (+28.7%). This surge was favored by the equivalence certification re-issued by NOAA on May 11, 2026 for Vietnam's live crab fishery. Meanwhile, shellfish reached US$25.6 million for the month (+21,4%), totaling US$178 million in the first seven months (+29.5%).
Source: VASEP
Breakdown by Destination Markets
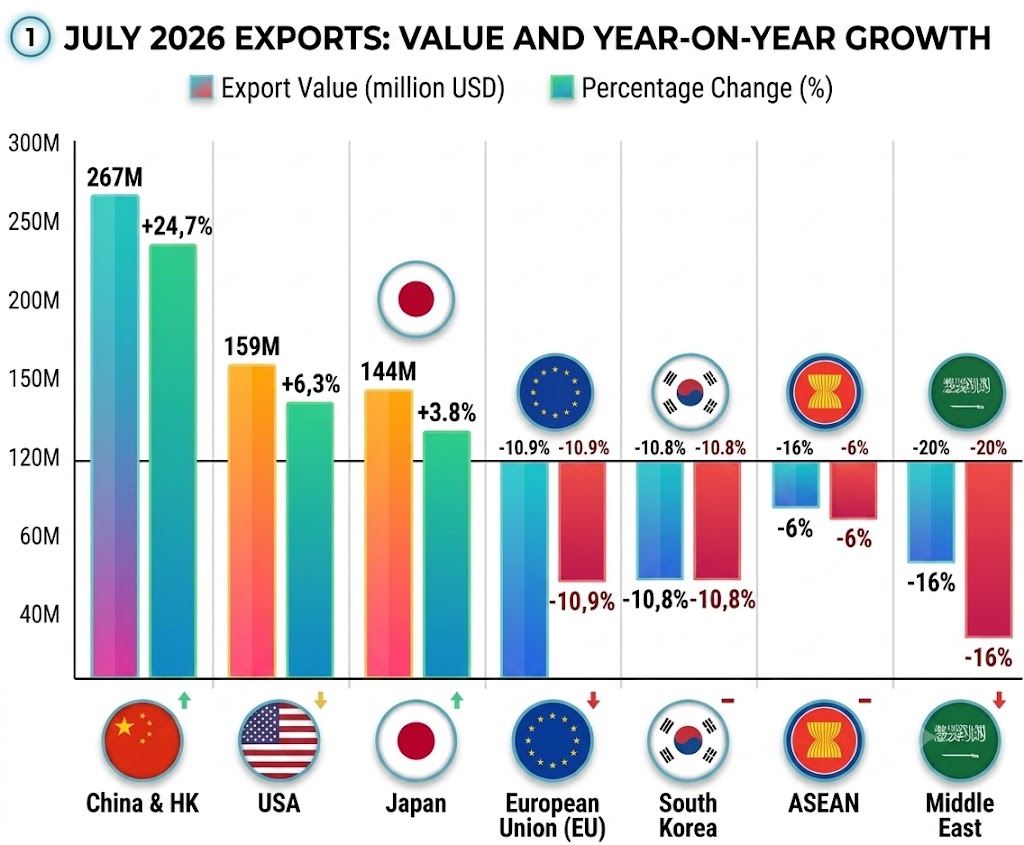
In the geographical analysis released by VASEP, China and Hong Kong consolidated their position as the primary export destinations in July, totaling over US$267 million (+24.7%). During the first seven months, purchases from this market reached US$1.74 billion (+34.5%), providing a net increase of over US$445 million that sustained the industry's overall growth.
For its part, the United States recorded shipments of US$159 million in July (+6.3%), accumulating US$1.05 billion (+0.3%). Japan reached US$144 million for the month (+3.8%), while the CPTPP block totaled US$1.783 billion (+8.1%) over the seven months.
In contrast, exports to the European Union dropped 10.9% in July (-2.7% cumulative), South Korea fell 10.8%, the ASEAN region declined 6%, and the Middle East retreated 16%
Outlook for the Close of 2026
Despite maintaining the goal of exceeding US$12 billion annually thanks to the cumulative US$6.784 billion through July, the momentum of Vietnam's fisheries exports will tend to slow in the final stretch of 2026.
Commercial contract adjustments, the tariff disadvantage against Ecuador, India, and Indonesia, and accumulating traceability demands in Europe and the United States will define processor margins in the coming months. Although Vietnam enacted regulations banning imports produced with forced labor starting September 2026 to strengthen talks with Washington, VASEP notes there is no official information indicating an immediate revision of the 12.5% tariff surcharge in the short term.
🇯🇵 日本語 (Japanese Version) | AIによる自動翻訳
7月のベトナム水産物輸出額は10億ドル超を維持、米関税により減速へ
第301条に基づく関税引き上げ、エクアドルとの競争、欧州における規制の厳格化が、2026年後半に向けて複雑なシナリオを提示している。
ハノイ — 2026年7月のベトナム産水産物の輸出額は前年同期比4.8%増の約10億2,000万米ドルに達した。これにより、年初の7か月間の累計輸出額は前年同期比11.5%増の約67億8,000万米ドルに拡大した。月次ベースでの10億ドル突破は年間120億米ドル超えという業界目標を裏付けるものであるが、成長ペースの鈍化が顕著になりつつある。
ベトナム水産物輸出生産者協会(VASEP)のレ・ハン副事務局長が発表した報告書によると、最も急速な成長期は過ぎ去った可能性がある。パンガシウス(Pangasianodon hypophthalmus)の7月の輸出額は6.1%減少し、マグロ類(Thunnus / Katsuwonus pelamis)の出荷はほぼ横ばいで推移した。また、欧州連合(EU)、韓国、中東向けの輸出はいずれも2桁の減少となった。
この減速に加え、米国における規制強化の影響も懸念されている。米国では7月24日より、通商拡大法第301条に基づき、ベトナム産水産物に対して12.5%の追加関税が適用された。契約上の猶予や輸送期間の関係で7月の数字には全容が反映されていないものの、VASEPは8月以降および第4四半期にかけてその影響が明確化すると見込んでいる。
エビセグメントでの競争と関税圧力
7月のエビ輸出額は前年同期比4.5%増の4億2,800万米ドルを超え、年初7か月間の累計では12.6%増の約27億8,000万米ドルに達し、ベトナムの水産物輸出総額の約41%を占めた。しかし、7月の4.5%という増加率は7か月累計の成長率を大幅に下回っており、主に中国向けのバナメイエビ・イセエビ需要に支えられている。一方で、バナメイエビ(Litopenaeus vannamei)やウシエビ(Penaeus monodon)などの主力品種は、米国、EU、日本で激しい価格競争に直面している。
最大の競合国はエクアドルである。同国は有頭エビだけでなく、無頭、むき身、付加価値の高い加工品セグメントでも供給量を急増させている。これに加え、米国市場における税制上の不利も生じている。7月23日に米国通商代表部(USTR)が公表した決定に基づき、ベトナム産品には第301条に基づく12.5%の関税が適用されるのに対し、競合するエクアドル、インド、インドネシアへの適用税率は10%にとどまる。
この2.5%の税率差は、最恵国待遇(MFN)関税やアンチダンピング税、相殺関税と重複するため、利益率の低い冷凍エビ取引において大きな打撃となる。このため、米国の輸入業者はベトナムの供給元に対してFOB価格の値下げ、税負担の折半、契約期間の短縮などを求める動きを強めている。
パンガシウスの機運と欧州の規制課題
パンガシウス(Pangasianodon hypophthalmus)セグメントの7月の輸出額は6.1%減の約1億8,400万米ドルとなったが、年初7か月間の累計では8.8%増の約13億米ドルを維持した。7月の減少は、中国市場での大型サイズの調整や、米国市場の緩やかな回復傾向を反映している。
しかし、欧州市場における白身魚の供給不足を受け、パンガシウスには戦略的な代替機会が浮上している。大西洋タラ(Gadus morhua)、コダラ(Melanogrammus aeglefinus)、アラスカスケソウダラ(Gadus chalcogrammus)の価格は、漁獲枠の削減やロシア産原材料の供給制限により高止まりしている。これにより、EUの加工業者は加工食品や外食産業向けにパンガシウスやティラピアの導入を検討している。
ただし、VASEPは欧州市場への参入には厳格なトレーサビリティ基準の適用が不可欠であると指摘する。2026年1月10日より、EUの輸入業者は関税分類の第3類および1604・1605に該当する水産物について、電子システム「CATCH」を通じて漁獲証明書を提出することが義務付けられた。養殖パンガシウスに直接適用されるわけではないが、天然水産物に対する確認手続きの厳格化は、欧州市場での競争環境に影響を与えている。
マグロおよびその他水産物の動向
マグロ類(Thunnus および Katsuwonus pelamis)の7月の輸出額は前年同期比0.1%減の6,900万米ドルを超え、年初7か月間の累計では1.4%減の約5億2,400万米ドルとなった。同セグメントは米国において、第301条に基づく12.5%の関税と、2026年1月1日に施行された海洋哺乳類保護法(MMPA)によるダブルパンチを受けている。
米国海洋大気庁(NOAA)は、ベトナムの一部漁業に対する同等性認定の不承認を確定した。これにより、該当する漁業からの対象製品には、適格証明書(COA)の添付が義務付けられている。またEU向けにおいても、違法・無報告・無規制(IUU)漁業に対するイエローカードや、EVFTAの原産地規則が引き続き輸出の障壁となっている。
対照的に、カニ・甲殻類セグメントは7月に前年同期比51.1%増(4,100万米ドル)と著しい伸びを示し、累計では28.7%増の2億4,600万米ドルに達した。この急増は、2026年5月11日にNOAAがベトナムの生体カニ漁業に対する同等性認定を再交付したことが寄与している。貝類も7月に21.4%増(2,560万米ドル)となり、累計で29.5%増の1億7,800万米ドルを記録した。
国・地域別輸出実績
VASEPが発表した地域別データによると、中国および香港が7月も最大級の市場であり続け、前年同期比24.7%増の2億6,700万米ドルを超えた。年初7か月間の累計は34.5%増の約17億4,000万米ドルに達し、業界全体の成長を力強く牽引している。
米国向けは7月に6.3%増の1億5,900万米ドル、累計では0.3%増の10億5,000万米ドルとなった。日本向けは7月に3.8%増の1億4,400万米ドル(累計2.6%増)、CPTPP域内向けは7か月累計で8.1%増の17億8,300万米ドルとなった。
一方で、EU向けは7月に10.9%減(累計2.7%減)、韓国向けは10.8%減、ASEAN向けは6%減、中東向けは16%減と、それぞれ縮小した。
2026年後半の見通し
年初7か月間で67億8,400万米ドルを達成したことで、年間120億米ドルの目標達成の可能性は残されているものの、2026年後半の伸び率は鈍化する見通しである。
商業契約の再交渉、エクアドル、インド、インドネシアに対する関税上の不利、さらには欧州および米国におけるトレーサビリティ要求の厳格化が、今後の加工業者の収益性を左右することになる。ベトナム政府は米国との協議を強化するため、2026年9月より強制労働によって生産された商品の輸入禁止措置を施行するが、VASEPによると、短期的には12.5%の追加関税が直ちに撤回される公式な見通しは立っていない。
🇨🇳 中文 (Simplified Chinese Version) | 由人工智能自动翻译
7月越南水产品出口额突破10亿美元 但受美国关税影响将放缓
依据301条款调升的关税、来自厄瓜多尔的竞争以及欧洲新的法规要求,为2026年下半年的出口前景带来了复杂挑战。
河内 — 2026年7月,越南 水产品 出口额达到近 10.2亿美元,与 2025年 同期相比增长 4.8%。凭此成绩,今年 前7个月 的累计出口额升至近 67.8亿美元,同比扩大 11.5%。尽管月度出口额再度突破10亿美元关口,进一步巩固了全年突破 120亿美元 的行业目标,但数据表明,高速增长期或已告一段落。
根据 越南水产出口与生产商协会(VASEP)副秘书长 黎恒(Le Hang)发布的报告,行业最具爆发力的增长阶段可能已经过去。查干鲶/巴沙鱼(Pangasianodon hypophthalmus)在 7月 的出口额下降了 6.1%,金枪鱼(Thunnus / Katsuwonus pelamis)出口基本持平。同时,发往 欧盟、韩国 和 中东 的出口均出现了 两位数 的下滑。
除了增速放缓外,美国 的监管政策也带来了显著冲击。自 7月24日 起,越南 水产品 正式被征收 301条款 项下的 12.5% 附加关税。由于合同签署和运输周期的滞后性,该税率的影响尚未完全体现在 7月 的数据中,但 VASEP 预计其负面效应将在 8月 及 第四季度 集中显现。
虾类领域的竞争与关税压力
7月 虾类出口额突破 4.28亿美元(+4.5%),前 7个月 累计出口额近 27.8亿美元(+12.6%),约占越南水产出口总额的 41%。然而,7月 4.5% 的单月增幅明显低于前7个月的平均水平,当前的主要增长动力来自于发往 中国 的龙虾出口。相比之下,凡纳滨对虾/南美白对虾(Litopenaeus vannamei)和斑节对虾(Penaeus monodon)在 美国、欧盟 及 日本 市场正面临极其剧烈的竞争。
最大的竞争压力来自 厄瓜多尔。该国不仅在带头虾领域大幅增加供应,在去头、剥皮及高附加值加工产品领域的出口量也在迅猛增长。除了直接的产品竞争,越南在关税上也处于劣势:根据 美国贸易代表办公室(USTR)在 7月23日 作出的决定,越南水产品在 301条款 下被征收 12.5% 的关税,而主要竞争对手如 厄瓜多尔、印度 和 印度尼西亚 的关税税率则为 10%。
2.5个百分点 的关税差距,叠加 最惠国(MFN)关税以及可能的反倾销税或反补贴税,极大地压缩了低利润冻虾产品的获利空间,促使 美国 进口商向越南供应商提出降低FOB价格、共同承担关税成本或缩短合同期限的要求。
巴沙鱼的前景与欧洲监管要求
在巴沙鱼(Pangasianodon hypophthalmus)领域,7月 出口额下降 6.1%,至近 1.84亿美元;不过前 7个月 累计出口额仍达到 13亿美元(+8.8%)。当月的下滑反映了中国市场对大规格鱼子需求的调整,以及美国市场复苏节奏依然缓慢。
尽管如此,面对欧洲市场底层白身鱼的紧缺,巴沙鱼正迎来战略性的替代契机。由于配额缩减以及俄罗斯供应链受限,大西洋鳕鱼(Gadus morhua)、黑线鳕(Melanogrammus aeglefinus)和黄线狭鳕(Gadus chalcogrammus)的价格居高不下。这促使 欧盟 的加工企业考虑增加巴沙鱼和罗非鱼的使用,以补充冷冻水产及餐饮服务的原料供给。
然而,VASEP 指出,进入欧洲市场的前提是严格符合可追溯性标准。自 2026年1月10日 起,欧盟 进口商必须通过电子 CATCH 系统,为海关编码 第3章 及 1604、1605 项下的 水产品 提交捕捞证书。尽管水产养殖的巴沙鱼不受野生捕捞证书的直接限制,但针对捕捞产品的审核趋严正深刻改变着欧洲市场的竞争格局。
金枪鱼及其他水产品的市场表现
金枪鱼(Thunnus 与 Katsuwonus pelamis)产业 7月 的出口额为 6900万美元(-0.1%),前 7个月 累计出口额近 5.24亿美元(-1.4%)。该产业在 美国 面临双重打击:一方面是 301条款 下 12.5% 的附加关税,另一方面是 2026年1月1日 生效的 海洋哺乳动物保护法(MMPA)规定。
美国国家海洋和大气管理局(NOAA)已确认拒绝授予越南部分渔业的等效认证。因此,源自相关渔业的产品必须随附合规证明(COA)。在欧洲市场,该产业则继续受到 打击非法、未报告和无管制(IUU)捕鱼黃牌警告以及 EVFTA 原产地规则的制约。
与此相对,螃蟹及甲壳类产品在 7月 实现了 51.1% 的显著增长(4100万美元),前 7个月 累计达到 2.46亿美元(+28.7%)。这一增长得益于 NOAA 于 2026年5月11日 重新颁发了对越南活蟹渔业的等效认证。贝类产品 7月 出口额达 2560万美元(+21.4%),前 7个月 累计达 1.78亿美元(+29.5%)。
按出口目标市场细分
在 VASEP 公布的地理区域分析中,中国 及 香港 依然是 7月 最大的出口目的地,总额超过 2.67亿美元(+24.7%)。前 7个月 累计进口额达到 17.4亿美元(+34.5%),带来了超过 4.45亿美元 的净增量,成为支撑越南水产业整体增长的主力。
美国 市场 7月 的出口额为 1.59亿美元(+6.3%),累计达 10.5亿美元(+0.3%)。日本 7月出口额达 1.44亿美元(+3.8%),CPTPP 成员国区域在前 7个月 累计达到 17.83亿美元(+8.1%)。
相反,发往 欧盟 的出口额在 7月 下降了 10.9%(7个月累计 -2.7%),韩国 下降 10.8%,东盟(ASEAN)下滑 6%,中东 区域则退缩了 16%。
2026年全年展望
虽然凭借前 7个月 累计的 67.84亿美元,全年突破 120亿美元 的目标依然可行,但越南水产出口在 2026年 剩余月份的增速预计将明显放缓。
商业合同的重新谈判、相比 厄瓜多尔、印度 和 印度尼西亚 的关税劣势,以及 欧洲 和 美国 日益严格的可追溯性要求,将共同决定未来数月加工厂的获利空间。尽管越南已出台法规禁止进口涉及强迫劳动生产的商品(自 2026年9月 生效),旨在加强与 华盛顿 的贸易对话,但 VASEP 表示,短期内尚无官方信息表明 12.5% 的附加关税会被立即调整。
[email protected]
www.seafood.media
Information of the company:
|
Address:
|
218 Road No.6, Zone A, An Phu An Khanh New Urban Area, District 2
|
|
City:
|
Ho Chi Minh
|
|
State/ZIP:
|
( )
|
|
Country:
|
Viet Nam
|
|
Phone:
|
+84 28 6281 0430
|
|
Fax:
|
+84 28 6281 0437
|
|
E-Mail:
|
[email protected]
|
More about: 
|
|
|
|



 Print